The Insurance Guy: Who Doesn't Love Homeowners Insurance?
In recent columns, we touched upon the importance of insuring buildings at proper limits, why it makes sense to spend a bit of time reviewing your auto and homeowners insurance, and what discounts and benefits are now available in a very competitive Massachusetts auto insurance marketplace.This month, I want to talk a bit about one of the products in the insurance world that I had always thought was actually a pretty good deal. Welcome to the HO-3 policy.
 More than just because the bank tells you that you must have a homeowners policy when you carry a mortgage, the homeowners plan is a smart way to manage risk by paying pennies on the dollar to protect your assets. First and foremost, the policy steps in if there is damage to your home that occurs from a few of the obvious causes of loss.
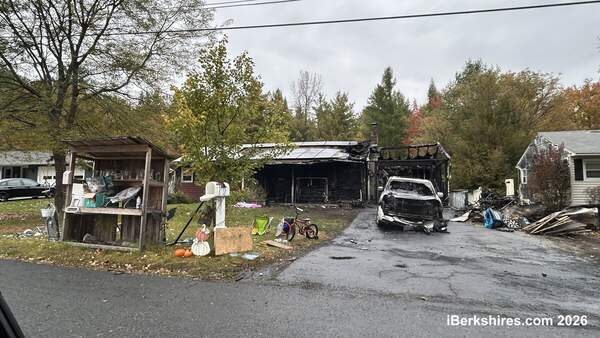
Most people would agree that damage from a fire would be the first job that a homeowners policy would perform. And that is true. If your home suffers partial or total damage from a fire, there is no better way to make you whole again than by having a properly written homeowners policy in place. And whether that premium is $500 or $1,200, if it affords you a couple of hundred thousand dollars in protection, it is a very good return on your premium. Not that I would wish a fire on anyone.
Wind damage is also typically covered by a homeowners policy and we know some of the damage that wind has done lately. Typically, water damage is not covered unless you have a separate flood policy, which can be a confusing topic for consumers. (We will cover water and flood in a separate column soon). However, you can have limited coverage added to your policy that may reimburse you for backup of water in a basement. Again, you really should consult your local agent.
The homeowners policy will also provide coverage to other structures such as detached garages, sheds, and other buildings that you may have on your property. It may also provide you, at the time of a loss, with compensation to provide temporary food and shelter that your family may need if you cannot remain in the home. These are benefits that become very important if you are ever involved in a serious loss at your home.
The homeowners policy also provides the insured with liability protection in case there is bodily injury or property damage done to a third party. This is where legal bills and damages may be paid from in the case of someone getting injured on your property, or being bit by your dog, or accidentally hit with a stray golf ball from your hooked drive at the golf course. There is also a medical payment portion of the policy where small medical bills can be paid to injured parties. The homeowners policy can be a very powerful tool when things hit the fan.
You may notice that there is an increase in the pricing on many homeowners policies, but it still remains a very good value for the consumer. There are a few reasons for the increase in pricing, primarily the fact that 2011 was a record year for catastrophes throughout the world. According to the Insurance Information Institute, worldwide events caused $350 billion in economic losses, shattering the 2005 record of $230 billion. The other primary reason is that the cost of rebuilding homes has gone up. According to Travelers Insurance, in the last year paint has gone up 4.5 percent, copper pipe up 19 percent, wire and cabling up 19.4 percent, insulation up 12.3 percent, and asphalt shingles up 8.3 percent.
But, there remain great deals out there if you are willing to spend some time and work with a local independent insurance agent. Happy home owning.
Dave Bissaillon dabbles in real life while working daily as an account executive at Smith Bros.-McAndrews Insurance Agency in Adams. His occasional column will touch on insurance and other fun stuff.
Tags: homeowners insurance,